Memorandum
- From
- Delaney Sawyer via Fortune | FORTUNE
- Date
- Filed
- Economy·6 min to read
- Re
Goldman Sachs: Labor's Share of U.S. Income Hits Record Low as Capital Ownership Rewards Narrow Elite
ReGoldman Sachs: Labor's Share of U.S. Income Hits Record Low as Capital Ownership Rewards Narrow Elite
Goldman Sachs research finds labor's share of nonfarm business income fell to a record 52.8% in Q2 2026, with about 60% of the decline driven by real structural shifts—rising corporate markups, automation, and weakened worker bargaining power—while the wealthiest 10% of households own most corporate equities, leaving most Americans unable to benefit from capital gains.
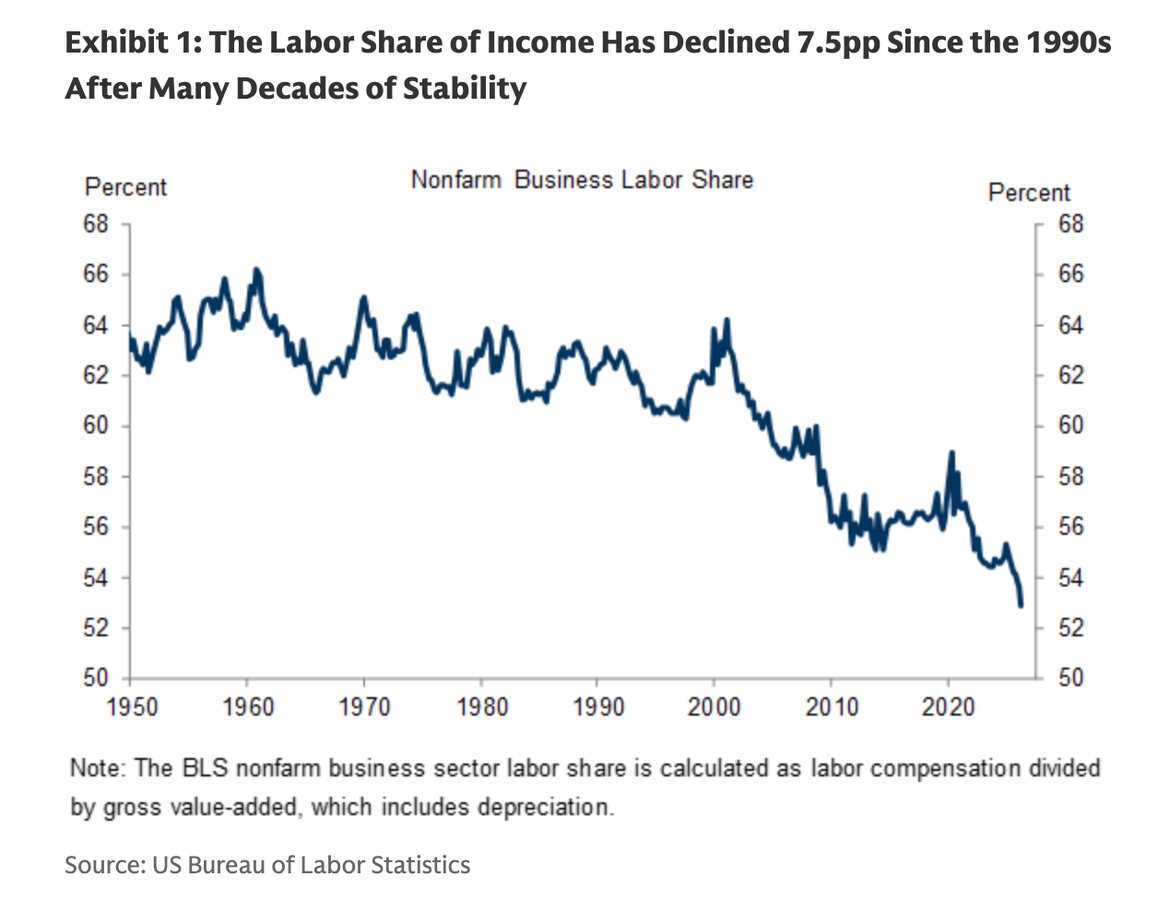
American workers are capturing the smallest slice of the nation's economic output since the government began tracking the measure in 1947, and a new Goldman Sachs analysis suggests most of that decline reflects a real shift in bargaining power toward capital owners—a shift that benefits only a narrow slice of households.
According to Bureau of Labor Statistics data cited in a September 15 Goldman Sachs research note, the labor share of income in the nonfarm business sector has fallen roughly 7.5 percentage points since the 1990s. BLS data released in early September put labor's share of nonfarm business output at just 52.8% to 52.9% in the second quarter of 2026, the lowest reading on record.
But Goldman economist Abhay Duggirala estimates that roughly 40% of that 7.5-point drop reflects measurement quirks in how the government counts wages and profits, not an actual transfer of income from workers to capital owners. The remaining 60%, or about 4.5 percentage points, is real, Goldman concludes, and it traces mostly to rising corporate markups, automation, and the decades-long erosion of workers' bargaining power.
The report, titled «What Explains the Decline in the Labor Share of Income?,» adds a key piece of evidence to a question gripping the 2020s: is the American middle class actually shrinking? The answer, this data suggests, is yes—but not for the reason most people assume.
Goldman's case for discounting nearly half the decline rests on three accounting distortions. The first is a tax-driven relabeling of income. Research by economist Matthew Smith and coauthors found that the 1986 Tax Reform Act, which raised the relative tax burden on C-corporations, pushed a wave of business owners into pass-through structures like S-corporations and partnerships. Income that once showed up as wages now gets reported as business profits instead—the same dollars, filed under a different label.
This is the mechanism at the center of economists Eric Zwick and Owen Zidar's research on «everywhere millionaires»: pass-through business owners, not celebrity billionaires, who have driven the lion's share of growth in top-1% income. Zwick told Fortune the tax code «places a lot more burden on salaried/wage-rate workers than other types,» pushing activity out of the W-2 bucket at both ends of the income scale—into pass-through business income at the top and into contract and part-time work at the bottom.
The second distortion involves depreciation. The BLS labor-share measure divides labor compensation by gross value-added, a figure that includes depreciation costs. As computers, software, and other short-lived capital goods have become a bigger share of the economy's capital stock, the overall depreciation rate has climbed, mechanically dragging down the labor share even though rising depreciation doesn't mean capital owners are pocketing more net income.
The third is equity compensation. The BLS only counts stock-based pay when it vests or is exercised, not when it's granted, so official wage data understates what high earners actually receive as their compensation increasingly shifts toward equity. Some of what looks like capital income is still labor income, just paid in stock—but it overwhelmingly flows to people positioned to get stock benefits, and those aren't people from traditional middle-class backgrounds.
The remaining 60%, another 4.5 points, reflects genuine structural change, according to Goldman: rising markups tied to «superstar» firms, automation reducing the need for labor, and weakened worker bargaining power from de-unionization and employer concentration.
The wealthiest 10% of American households hold the vast majority of corporate equities and mutual fund shares, according to Federal Reserve data, meaning the superstar-firm profits Goldman credits with driving much of the shift accrue overwhelmingly to a narrow slice of already-wealthy shareholders—not to the broader workforce whose labor share is shrinking.
So what does this mean for the supposedly shrinking middle class? In January, the Congressional Budget Office found the top 1%'s share of income before taxes and transfers doubled between 1979 and 2022, while the middle three income quintiles' after-tax share fell 6 percentage points over the same period—a straightforward hollowing-out story, driven largely by capital gains concentrating at the very top.
But other research complicates that picture. In April, an American Enterprise Institute report by economists Stephen Rose and Scott Winship found the opposite: the «shrinking» middle class wasn't falling behind; it was moving up, with the upper-middle-class share of families tripling from 10% to 31% between 1979 and 2024 and median family income rising 52% over the same period.
Buried inside that optimistic report was an uncomfortable admission: the combined income share of the middle three quintiles has still declined, even as more families climb into the upper-middle tier. The result is an America that has grown genuinely wealthier by nearly every historical measure, yet is struggling to feel it, recognize it, or convert it into the kind of security and status that used to come standard with a paycheck.