Memorandum
- From
- Delaney Sawyer via Fortune | FORTUNE
- Date
- Filed
- Economy·5 min to read
- Re
Bill Gross Warns Against Holding Long-Term Bonds as Debt Hits $84 Trillion
ReBill Gross Warns Against Holding Long-Term Bonds as Debt Hits $84 Trillion
The investor known as the «Bond King» says government, mortgage and corporate credit have grown unbalanced, and advises caution on long-term debt and record-high stocks.
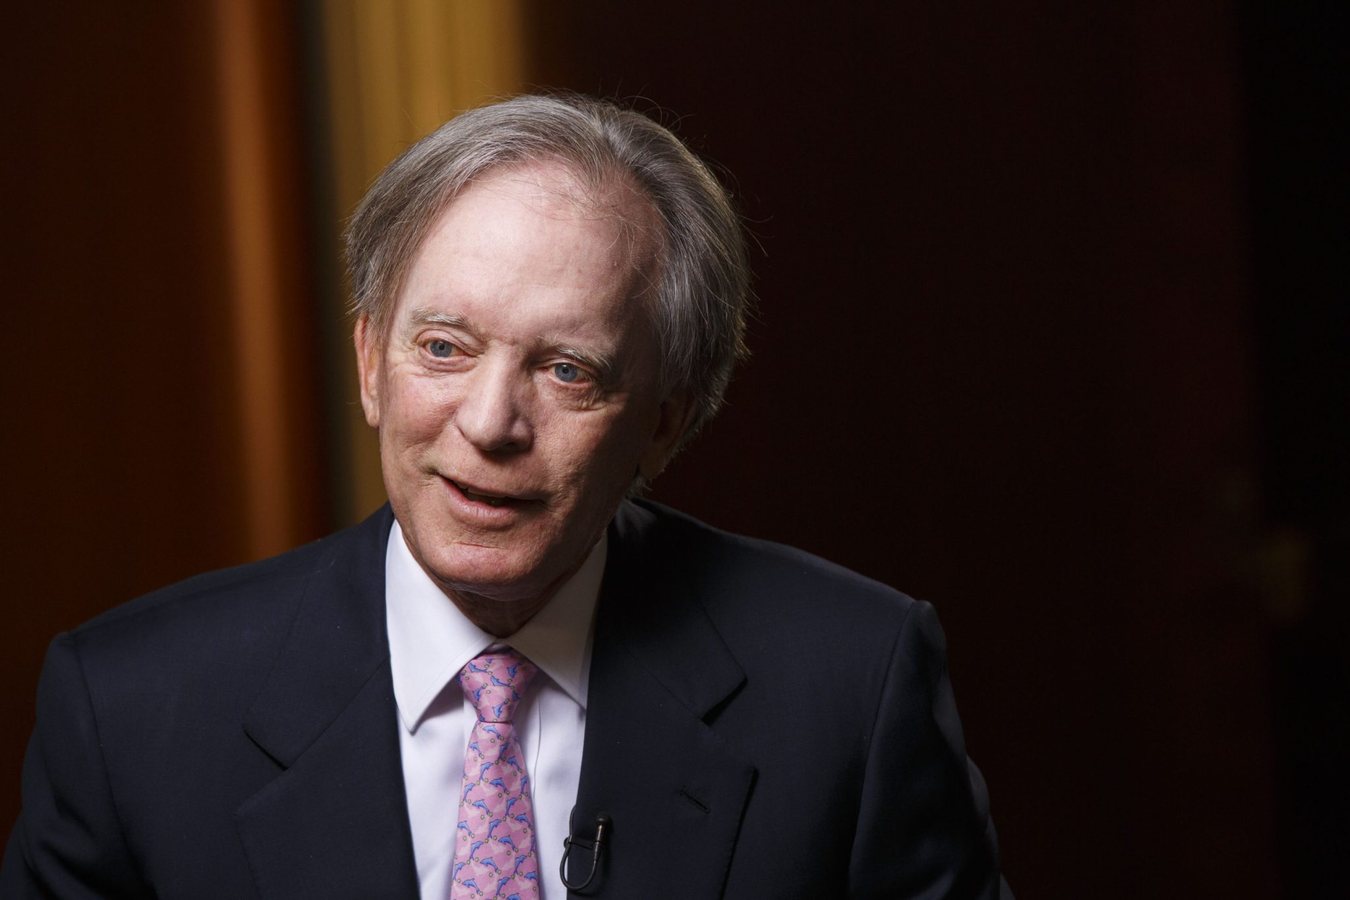
Bill Gross, the PIMCO cofounder who earned the nickname «Bond King» by transforming bond investing, is warning that the global credit landscape has become dangerously lopsided and that investors should avoid longer-term debt. In an op-ed published Wednesday in the Financial Times, Gross noted that government, mortgage and corporate credit now totals roughly $84 trillion, a figure he says reflects a dangerous imbalance between debt and equity.
«Too much debt can lead to too much risk and too much equity can lead to less earnings per share growth under certain underperforming productivity cycles,» Gross wrote. He argued that when debt and equity move at the same pace consistent with industry standards and economic growth, the economy is more likely to expand. But balance sheets have grown too lopsided, putting that growth at risk.
The warning carries unusual weight because of its source. Gross spent decades dominating a corner of financial markets that was considered sleepy before his arrival, using active trading strategies that generated returns far beyond simply buying bonds and holding them to maturity to collect interest. His admonition that investors should not own bonds is therefore notable coming from the man who built his career on them.
Gross pointed to several specific concerns. The artificial intelligence sector's debt boom is an anomaly by historical standards, and federal debt has already reached peak levels for peacetime, now at 100% of GDP. While all that borrowing is fueling growth today, it has contributed to higher inflation and will likely slow growth in the future, he added.
«In such an environment, my view is: don't own bonds, with the exception of one-year Treasury bills, which are now at 4.55%,» Gross said. He also advised caution on stocks at record levels, warning that higher yields over time will contract profit margins. «Be prepared for the end of 'what you are used to' stock markets and higher volatility in prices for the benchmark 10-year Treasury bonds,» he wrote.
The bond market itself has undergone a transformation that supports Gross's concerns. Central banks around the world no longer reliably buy and hold Treasury debt as they seek to diversify their reserves. At the same time, price-sensitive hedge funds have emerged as bigger players and are quicker to sell. The so-called basis trade, in which hedge funds profit from small price differences between Treasury bonds and Treasury futures, has made the market more volatile. Hedge funds' share of total Treasury holdings has almost doubled since 2023 to 8.5%, exceeding the portion held by depository institutions and mutual funds.
That new era of volatility has been on display this year. Ten-year Treasury yields have soared more than 100 basis points since the Iran war started and recently hit the highest levels in 24 years. Joe Maher, markets economist at Capital Economics, said in an August note that while hedge funds are a key source of liquidity, they may weaken bonds' reputation as a safe-haven asset. «In a risk-off environment, safe-haven flows into sovereign bonds may be offset by hedge funds unwinding their leveraged trading positions as funding conditions tighten,» Maher wrote. «And given they have no obligation to act as market makers, the more likely it is that liquidity dries up in these markets in times of stress.»
Maher also warned that hedge funds could transmit stress across different assets. A stock market selloff, for example, could force hedge funds to dump bond positions to cover losses in equities.
Gross said he is suspicious of AI hyperscalers unless they have price-to-earnings ratios of less than 20. He noted that while stocks like Verizon and AT&T have decent yields, their mobile phone businesses are threatened by SpaceX's Starlink. Some income funds trading at a discount to net asset values may offer opportunities, but they would suffer if short-term interest rates rise higher than expected, he added.
«Preserve and protect is my current investment motto,» Gross wrote.
5