Memorandum
- From
- Delaney Sawyer via Fast Company
- Date
- Filed
- Economy·4 min to read
- Re
54 of 300 Largest US Housing Markets See Home Prices Fall
Re54 of 300 Largest US Housing Markets See Home Prices Fall
Home prices are down year over year in 54 of the nation's 300 largest metro housing markets, even as national appreciation holds at a soft +1.3%, according to an analysis of the Zillow Home Value Index.
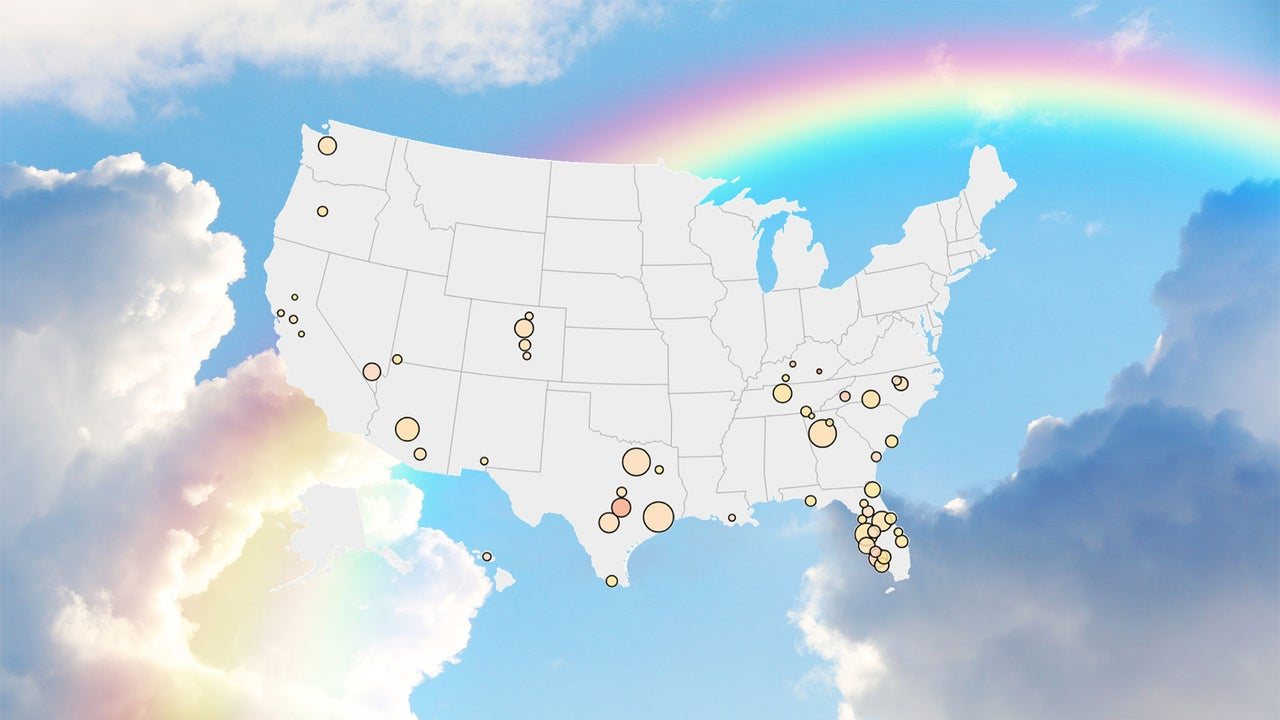
Home prices are falling on a year-over-year basis in 54 of the nation's 300 largest metro housing markets, even as the national aggregate continues to climb at a modest pace. The declines represent 18% of the largest markets, according to an analysis of the Zillow Home Value Index covering the twelve months through August 2026.
Nationally, home prices are up 1.3% year over year, a rate that remains soft but has edged slightly higher from a year earlier, when the national reading sat at roughly flat. The split between rising and falling markets is wider than usual, with 246 of the 300 largest metros still posting annual gains while the remaining 54 slip into negative territory.
The geography of the softness is concentrated. Many of the markets where buyers have gained the most leverage since the pandemic housing boom cooled are in Sun Belt regions and the Mountain West. Those areas saw some of the sharpest price surges during the boom, with appreciation outpacing local incomes. As pandemic-era migration slowed and mortgage rates rose in 2022, markets such as Tampa and Austin came under pressure, forced to rely on local earnings to support elevated prices.
New construction has compounded that cooling. Builders in the Sun Belt have been willing to cut prices or offer affordability incentives to keep sales moving, which in turn weighs on the resale market. Some buyers who might previously have purchased an existing home are instead choosing new construction with more attractive terms, adding further upward pressure to resale inventory.
The count of declining markets has begun to stabilize over the past year, and inventory growth has decelerated. In fall 2025, the expectation was that the number of markets with annual price declines would gradually shrink a little in the first half of 2026, and that is what has played out. The national market remains soft, but the burst of softening has eased.
Regional divergence remains pronounced. Prices are still climbing modestly in many areas where active inventory sits well below pre-pandemic 2019 levels, including pockets of the Northeast and Midwest. By contrast, some areas in Texas, Florida, and Colorado, where active inventory exceeds 2019 levels by a solid margin, are seeing material corrections, modest pullbacks, or flat pricing.
The gap between resilient and weaker markets can widen the longer they stay on opposite tracks. Home prices in the Hartford, Connecticut, metro area now stand 29.0% above their 2022 peak, while prices in the Austin, Texas, metro area sit 27.6% below their 2022 peak. Much of that bifurcation reflects mean reversion, with the steepest declines occurring in markets that overheated most during the pandemic boom.
The historical pattern shows how unusual the current period is. In the twelve months through August 2021, none of the 300 largest markets posted a falling year-over-year reading. That figure rose to 78 markets in the 2022–2023 window and peaked at 109 markets in the 2024–2025 window before easing to the current 54.
The key question going forward is whether another burst of national softening emerges, given that the 30-year fixed mortgage rate has climbed back above 7.00%. Monitoring local active inventory over the coming months will be the clearest signal of where prices head next.
3